
Membrane Filtration Market Acceleration Through 2035: Global Demand for Water Security and Industrial Reuse
The global membrane filtration market enters 2026 driven by broader demand fundamentals, more disciplined purchasing behaviors, and a more regionally diversified supply structure. This article is a translation and analysis based on the comprehensive report by the IndexBox Institute.
The global membrane filtration market begins the 2026–2035 forecast period as a mature yet structurally expanding segment within the separation technology industry; where demand is increasingly underpinned by regulatory compliance, water security, and process intensification rather than discretionary capital expenditures.
This market encompasses pressure-driven separation processes including microfiltration, ultrafiltration, nanofiltration, reverse osmosis, electrodialysis, and gas separation, offered through spiral, hollow fiber, tubular, and plate-and-frame modules, alongside replacement elements, cartridges, and integrated system services.
Based on the 2026 baseline, the market growth profile is shaped by three intersecting forces:
First, municipal and industrial water reuse mandates that transform membrane filtration from an optional efficiency lever into a licensing requirement in water-stressed basins.
Second, the sustainable development of desalination capacity in the Middle East, North Africa, and coastal Asia-Pacific regions, where reverse osmosis remains the dominant technology.
Third, the expansion of biopharmaceutical production and food and beverage processing, where requirements for sterile filtration and purification are becoming increasingly stringent.
Competitive dynamics remain centered among diversified industrial and water technology conglomerates, but specialized module manufacturers and service providers are capturing a larger share of the value in replacement parts and maintenance. The forecast horizon to 2035 assumes no sudden technological substitution and a continued gradual decline in unit membrane costs.
This report provides a data-driven assessment of market size, segmentation, supply chain structure, and regional demand. The baseline forecast assumes the market will continue to grow at a moderate, single-digit compound annual growth rate, with the market index rising from 100 in 2025 to a higher level by 2035.
The water and wastewater treatment segment remains the largest volume anchor, but the fastest gains are expected in industrial process separation and biopharmaceutical manufacturing. Municipal capital budgets in developed economies are gradually shifting from new construction toward replacement and upgrade cycles.
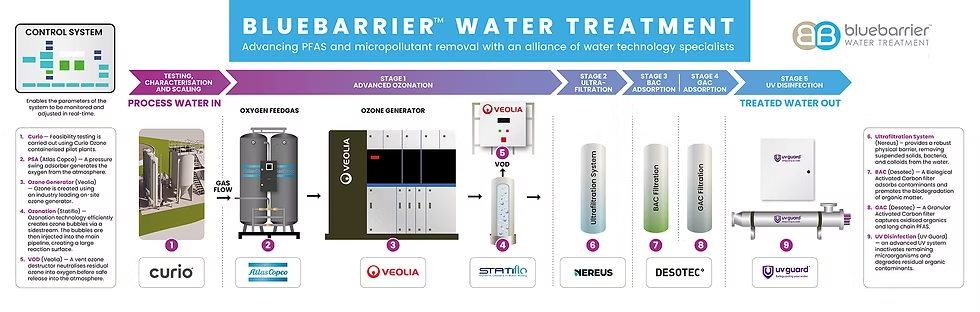
In emerging markets, particularly in Asia-Pacific and the Middle East, new desalination and reuse plants are the primary volume drivers. The main uncertainty in the baseline scenario is the speed at which effluent quality oversight and PFAS-related treatments intensify, which could accelerate replacement demand in North America and Europe.
Demand Drivers and Constraints
Key demand drivers include the intensification of municipal and industrial water reuse and discharge regulations, the sustainable development of desalination capacity in water-stressed coastal regions, and the expansion of biopharmaceutical construction. Furthermore, industrial reuse and resource recovery goals in the chemical industry play a key role.
Conversely, potential growth constraints include high initial capital costs, membrane fouling challenges that inflate operating costs, and price-competitive pressure in the mature microfiltration and ultrafiltration segments.
Demand Structure by End-User Industry
Water and Wastewater Treatment (Estimated Share: 38%): This is the largest end-use segment for membrane filtration, anchored in municipal drinking water plants and industrial wastewater treatment. Major trends include a shift from new construction to upgrade expenditures and increasing adoption of membrane bioreactors. Representative players include SUEZ, Veolia, and DuPont Water Solutions.
Industrial Process Separation (Estimated Share: 22%): This segment includes membrane applications in chemical, mining, pulp and paper, and textile industries, where membranes are used for concentration, purification, and recovery of water and process chemicals. The key driver is the economics of resource recovery. Representative players include Koch Separation Solutions, Veolia, and Asahi Kasei.
Food and Beverage Processing (Estimated Share: 15%): Food processing utilizes membrane filtration for clarification, concentration, and microbial stabilization in dairy, beverage, and sugar production. This segment is supported by sustained demand for product quality preservation and shelf-life extension. Companies such as Toray Industries and Pall Corporation are active in this field.
Biopharmaceutical Production (Estimated Share: 14%): Biopharmaceutical production is heavily dependent on membranes for sterile filtration and buffer preparation. This segment records the fastest growth among end-use segments. Companies such as Sartorius and Merck KGaA are key players in this area.
Desalination (Estimated Share: 11%): Desalination is a structurally growing segment dominated by reverse osmosis. Demand growth is concentrated in the Middle East, North Africa, and Asia-Pacific. Companies like LG Chem and Toyobo are major players in this sector.
Regional Dynamics
Asia-Pacific (Estimated Share: 34%): The largest and fastest-growing regional market, supported by desalination capacity development in China and India and water reuse requirements.
North America (Estimated Share: 24%): A mature yet resilient market focusing on system replacement and upgrades, with attention toward PFAS-related contaminant treatments.
Europe (Estimated Share: 21%): Shaped by stringent water quality and reuse regulations that facilitate membrane adoption in municipal and industrial sectors.
Middle East and Africa (Estimated Share: 13%): The primary desalination region with large-scale reverse osmosis projects driven by severe water scarcity.
Latin America (Estimated Share: 8%): Demonstrates moderate growth focusing on municipal water treatment and mineral process separation.
Exclusive Analysis by the Water Insight Hub Team
The global implication of this report is that membrane technologies are no longer a luxury option; they are the backbone of water security on a global scale. Given the mounting water scarcity challenges, which are also highlighted in analytical reports by the United Nations, the expansion of this market is inevitable.
The deep link between this market and water technology suggests that suppliers must pivot toward offering smart and digital solutions. Data-driven monitoring and preventive maintenance are the keys to reducing the lifecycle costs of membrane systems.
The outlook for the MENA region again highlights the critical importance of reverse osmosis-based desalination projects. Countries in the MENA region, relying on advanced innovation, are working to ensure the sustainability of their freshwater resources.
The implication for the MENA region, given severe water resource crises and the urgent need for consumption management, doubles the necessity of leveraging global experiences in wastewater reuse and advanced filtration systems. Adopting modern approaches in industries can prevent environmental disasters.
The final conclusion affirms that the membrane filtration market will follow an upward, sustainable trend through 2035, based on strict environmental standards, with primary value creation concentrated in the service and maintenance sector.
 Official Email of the Water Insight Hub: